“Zero income tax country” might sound appealing to a wealthy person seeking to optimise their tax burden. However, there are several things to be considered when choosing a low-tax country to live in: the general lifestyle of the country, other taxes it imposes on its residents, and the availability of residence or citizenship for foreigners.
Immigrant Invest experts share their ratings of the best tax-free countries to live in and an overview of other options.
Country without income tax: is it possible?
Taxes are among the most popular means for a country to make money, and income tax usually plays a substantial role in it. However, some countries do not impose income tax on their citizens and residents. It is possible when a state makes enough money through other means.
Some countries, like Qatar and Kuwait, are rich in natural resources and earn from their oil and gas trade. Others, like the Bahamas, attract enough tourists to raise substantial money from that sector. Lastly, countries with no income tax for foreigners under the law can also be a government choice to attract investors to the country.
There are currently 17 countries in the world with zero income tax. Among them are Antigua and Barbuda, St Kitts and Nevis, the UAE, Vanuatu, Brunei, Bahrain, the Bahamas, Bermuda, the Cayman Islands, the Turks and Caicos Islands, the British Virgin Islands, Monaco, Saudi Arabia, Kuwait, Qatar, Somalia, and Western Sahara.
In addition to them, there are low-tax regions. This article will also give examples of countries with the lowest tax rates in the world.
Trusted by 10,000+ investors
Citizenship vs residence by investment: compare all options
17 best countries with no income tax: Immigrant Invest experts’ choice
A 0% personal income-tax rate does not automatically make a country tax-free for every investor. Other factors also matter, including how a person becomes a tax resident, which types of income remain untaxed, whether investors can obtain residence or citizenship, and how tax treaties may affect obligations in another country.
The rules differ from one jurisdiction to another. Some countries use clear day-count tests, while others look at where a person lives and has stronger personal or economic ties.
Tax-free countries for international investors

Country or territory

Personal income tax
0%
Capital gains tax
0%
Investor route
Citizenship by investment — $230,000+
Country or territory

Personal income tax
0%
Capital gains tax
0%
Investor route
Citizenship by investment — $250,000+
Country or territory

Personal income tax
0%
Capital gains tax
0%
Investor route
Citizenship by investment — $130,000+
Country or territory
 Bahrain
Personal income tax
0%
Capital gains tax
0%
Investor route
10-year Golden Residency — property worth BHD 200,000+
Country or territory

Personal income tax
0%
Capital gains tax
0% on personal investment gains
Investor route
Dubai property residence; 10-year Golden Residency — property worth at least AED 2 million
Country or territory
 Bahamas
Personal income tax
0%
Capital gains tax
0%
Investor route
Permanent residence — investment of over $1 million
Country or territory
 Bermuda
Personal income tax
0%; payroll tax applies
Capital gains tax
0%
Investor route
Indefinite residence — investment of over $2.5 million and charitable donation of $25,000+
Country or territory
 Cayman Islands
Personal income tax
0%
Capital gains tax
0%
Investor route
Permanent residence — real estate investment of over CI$2 million
Country or territory
 Monaco
Personal income tax
0% for most residents
Capital gains tax
0%
Investor route
Residence based on accommodation and financial resources
Country or territory
 Saudi Arabia
Personal income tax
0% on employment income
Capital gains tax
0% for private investment gains
Investor route
Premium Residency — business investment of over SAR 7 million or property worth over SAR 4 million
Country or territory
 British Virgin Islands
Personal income tax
0%; payroll tax applies
Capital gains tax
0%
Investor route
No residence or citizenship by investment
Country or territory
 Turks and Caicos Islands
Personal income tax
0%
Capital gains tax
0%
Investor route
Permanent residence — property investment of $300,000+ or business investment of $750,000+
Country or territory
 Brunei
Personal income tax
0%
Capital gains tax
0%
Investor route
No residence or citizenship by investment
Country or territory
 Kuwait
Personal income tax
0%
Capital gains tax
0%
Investor route
Long-term investor residence — qualifying company investment of over KWD 5 million
Country or territory
 Qatar
Personal income tax
0% on employment income
Capital gains tax
0% on qualifying personal gains
Investor route
Property residence — property worth more than QAR 730,000
Country or territory
 Anguilla
Personal income tax
0%
Capital gains tax
0%
Investor route
Permanent residence — contribution of $150,000+ or qualifying real estate investment
Country or territory
 Oman
Personal income tax
0%
Capital gains tax
0%
Investor route
10-year Golden Residency — investment of approximately $520,000+
Country or territory | Personal income tax | Capital gains tax | Investor route |
|---|---|---|---|
0% | 0% | Citizenship by investment — $230,000+ | |
0% | 0% | Citizenship by investment — $250,000+ | |
0% | 0% | Citizenship by investment — $130,000+ | |
| 0% | 0% | 10-year Golden Residency — property worth BHD 200,000+ |
0% | 0% on personal investment gains | Dubai property residence; 10-year Golden Residency — property worth at least AED 2 million | |
| 0% | 0% | Permanent residence — investment of over $1 million |
| 0%; payroll tax applies | 0% | Indefinite residence — investment of over $2.5 million and charitable donation of $25,000+ |
| 0% | 0% | Permanent residence — real estate investment of over CI$2 million |
| 0% for most residents | 0% | Residence based on accommodation and financial resources |
| 0% on employment income | 0% for private investment gains | Premium Residency — business investment of over SAR 7 million or property worth over SAR 4 million |
| 0%; payroll tax applies | 0% | No residence or citizenship by investment |
| 0% | 0% | Permanent residence — property investment of $300,000+ or business investment of $750,000+ |
| 0% | 0% | No residence or citizenship by investment |
| 0% | 0% | Long-term investor residence — qualifying company investment of over KWD 5 million |
| 0% on employment income | 0% on qualifying personal gains | Property residence — property worth more than QAR 730,000 |
| 0% | 0% | Permanent residence — contribution of $150,000+ or qualifying real estate investment |
| 0% | 0% | 10-year Golden Residency — investment of approximately $520,000+ |
1. Antigua and Barbuda
Tax rules. Aside from zero income tax, in Antigua and Barbuda, individuals are also free from paying taxes on wealth, capital gains, and inheritance[1]Source: Government of Antigua and Barbuda — Budget Statement 2022.
Standard corporate tax in Antigua and Barbuda is 25%.
Obtaining Antigua and Barbuda citizenship does not automatically exempt individuals from taxes in other countries. They may still have tax obligations in their country of original citizenship or tax residence, depending on its tax laws and their individual circumstances.
How tax residence is established in Antigua and Barbuda. An individual can qualify as resident if at least one of these conditions is met:
- they have a permanent home in Antigua and Barbuda and spend some time there during the year;
- they are physically present in the country for at least 183 days;
- their stay in Antigua and Barbuda forms part of a continuous 183-day period spanning two tax years;
- they spend at least 30 days in the country while holding a permanent resident certificate[2]Source: OECD — Antigua and Barbuda: Information on Residency for Tax Purposes.
Path to citizenship. Wealthy foreigners may obtain Antigua and Barbuda citizenship by investing $230,000 or more in the country’s economy[3]Source: Antigua and Barbuda Citizenship by Investment Unit — Citizenship.
The investor must be over 18, have a legal income, and have no criminal record.
Including the family in the application is also possible: a spouse, children under 30, parents and grandparents aged 55 or older, and unmarried siblings. Antigua and Barbuda citizenship is not inherited automatically, so the investor has to make sure to add all eligible family members within the first five years of obtaining citizenship.
Aside from the tax benefits, the Antigua and Barbuda passport allows its holders:
- to enter the Schengen countries visa-free and stay there for up to 90 out of 180 days;
- to visit the UK visa-free and stay there for 180 days;
- to travel visa-free to 166 countries altogether.
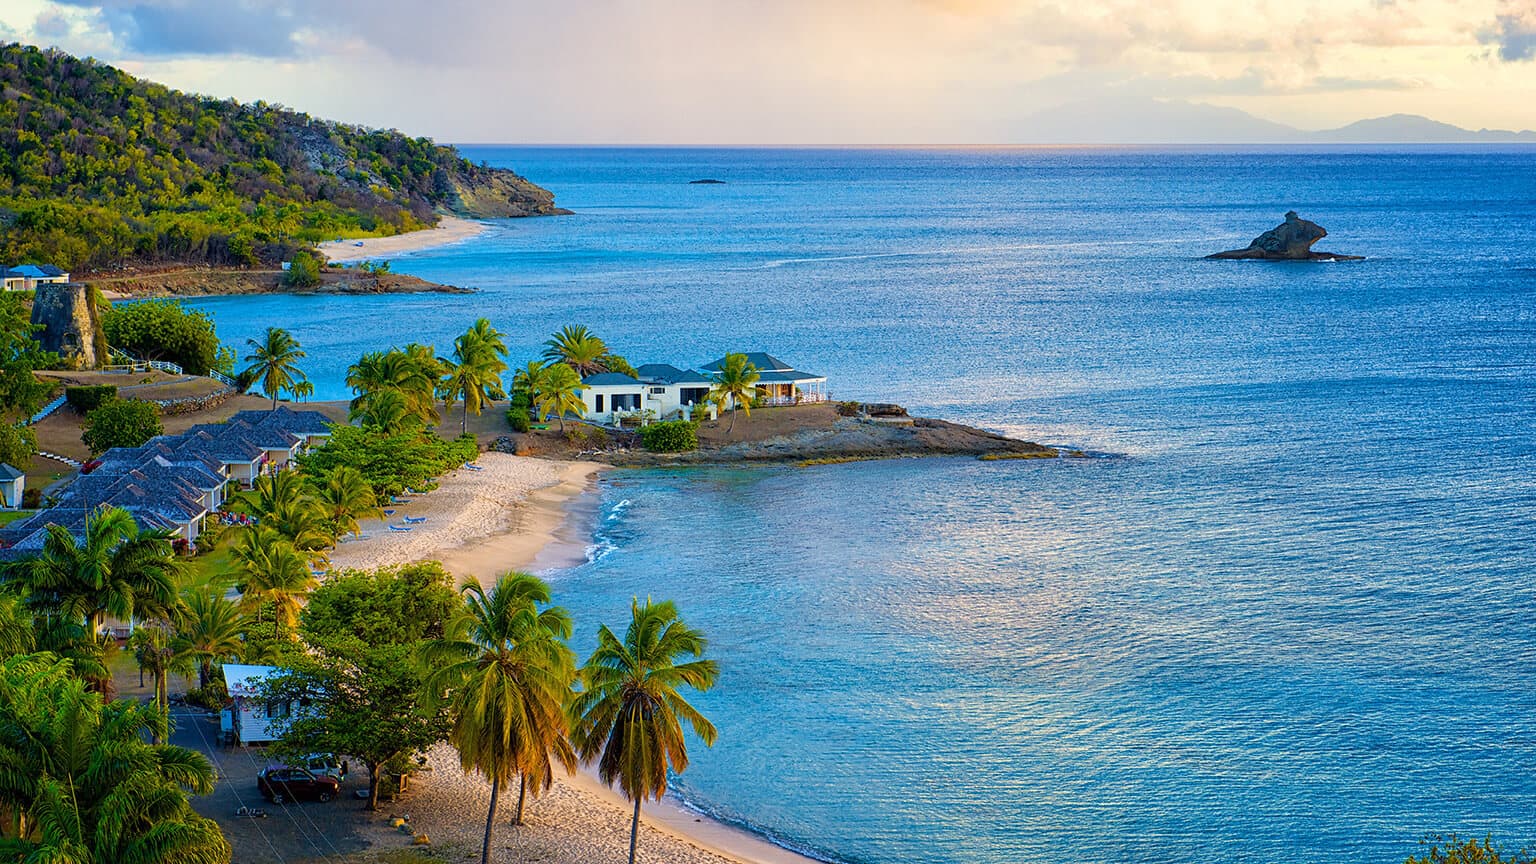
Antigua and Barbuda is a beautiful island state with pink and white sand beaches, coral reefs, and blue lagoons. The islands are famous for their comfortable marinas, and some celebrities love spending time there: for example, singer Eric Clapton and fashion designer Giorgio Armani bought houses there.

2. St Kitts and Nevis
Tax rules. St Kitts and Nevis has no taxes on income, dividends, royalties, or interest for residents. Corporate tax is 33%, VAT is 17%, and property ownership is taxed 0.2 to 0.3%[4]Source: St Kitts and Nevis Inland Revenue Department — Tax FAQs.
How tax residence is established in St Kitts and Nevis. Citizenship alone does not make an investor a tax resident. St Kitts and Nevis does not set a single number of days that automatically gives an individual tax-resident status.
Instead, the authorities consider whether the person actually lives in the country and has meaningful ties there, such as a permanent home. If another country also considers the person a tax resident, an applicable double-taxation treaty may look at where they have a permanent home, closer personal and economic ties, and where they usually live[5]Source: St Kitts and Nevis Law Commission — Income Tax Act, Cap. 20.22.
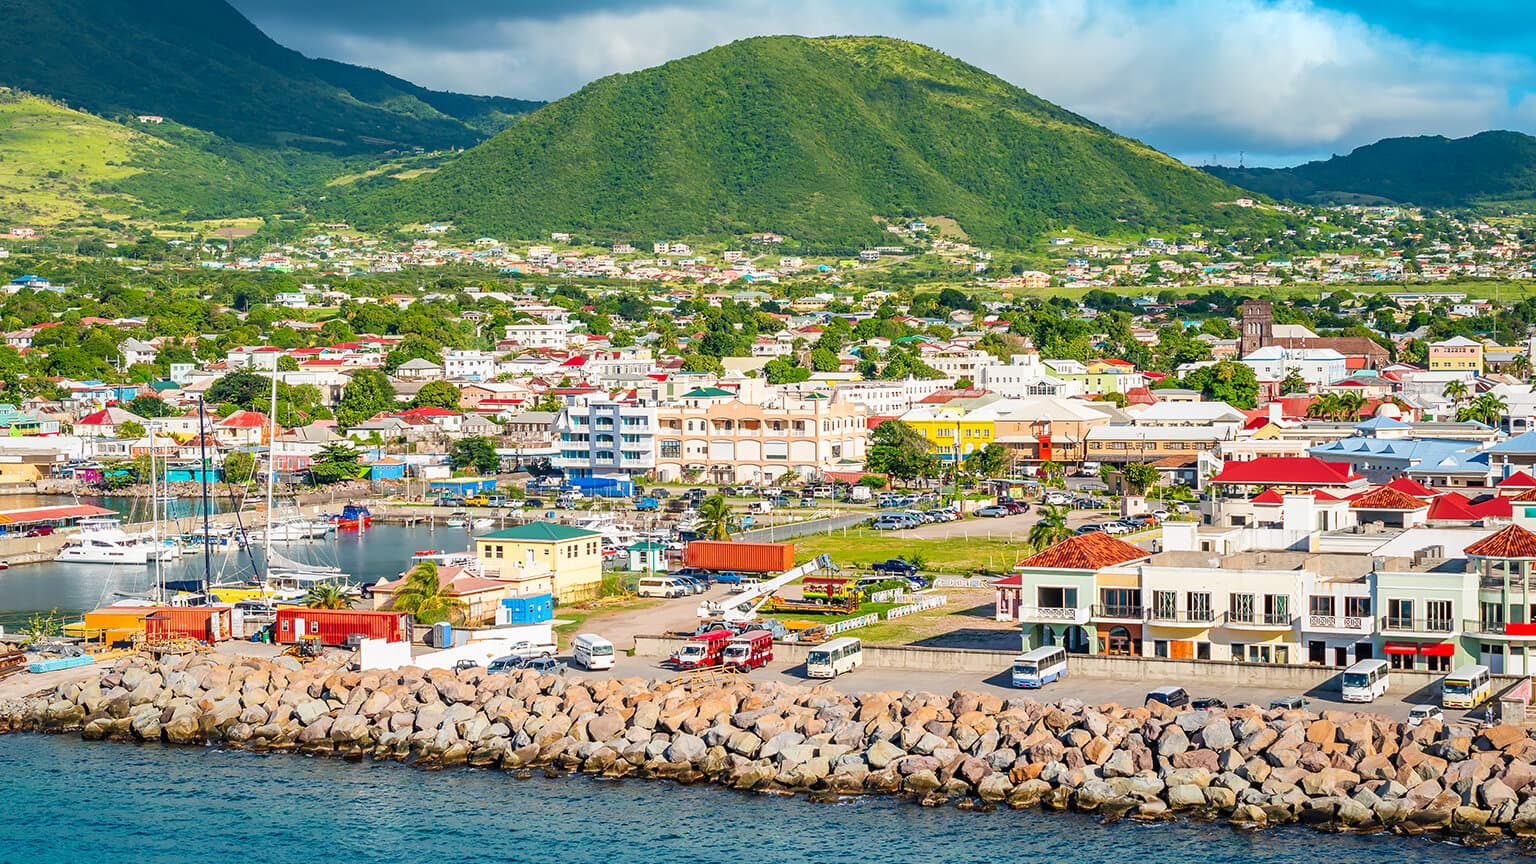
Path to citizenship. St Kitts and Nevis citizenship is obtainable by investment of $250,000+. The investor must be over 18, with legal income and no criminal record. It is also possible to include the family in the application: a spouse, children under 25, and parents aged 55 or older. The process of obtaining St Kitts and Nevis takes at least 4 months[6]Source: St Kitts and Nevis Citizenship by Investment Unit — Sustainable Island State Contribution.
The islands are famous for their picturesque nature: mountains, rainforests, and beautiful beaches with black volcanic sand. Travellers go to St Kitts and Nevis to sunbathe, dive, go on a yacht along the coasts, and try local foods. Regarding visa-free travelling, St Kitts and Nevis passport is among the strongest Caribbean ones.
3. Vanuatu
Tax rules. There are no taxes on personal income, inheritance, capital gains, and capital export for individuals. Companies can be exempt from corporate and other taxes for 20 years, only paying a $300 annual fee[7]Source: Vanuatu Customs and Inland Revenue — Guide for Reporting Financial Institutions.
However, Vanuatu hasn't concluded tax treaties with many states globally, so a person with a Vanuatu passport may be obliged to pay taxes in another country.
How tax residence is established in Vanuatu. The country treats an individual as a tax resident if they have a home in the country during the year or spend at least 183 days there within any 12-month period[8]Source: Vanuatu Customs and Inland Revenue — Guide for Reporting Financial Institutions, Section 4.
Pathway to citizenship. Vanuatu offers the fastest citizenship by investment programme — the second passport can be obtained in 2+ months by investing $130,000+[9]Source: Vanuatu Citizenship Office — Citizenship Fees and Charges.
The Vanuatu passport allows visa-free entry to 124 countries, including Singapore and Hong Kong. However, Vanuatu citizens will still need a visa to visit the Schengen countries and the UK.
4. Bahrain
Tax rules. Bahrain has no personal income tax. The standard VAT rate is 10%[10]Source: Bahrain National Bureau for Revenue — Value Added Tax.
Oil and gas companies pay 46% income tax. Since 2025, Bahrain has also applied a 15% domestic minimum top-up tax to multinational groups with annual consolidated revenue of at least €750 million in at least two of the previous four financial years.
How tax residence is established in Bahrain. An individual can obtain a Certificate of Residence for tax purposes if they spend at least 183 days in Bahrain during the year for which the certificate is requested.
Pathway to residence in Bahrain. Bahrain does not offer citizenship by investment. Foreigners who own property worth at least BHD 200,000, or approximately $530,000, can obtain a 10-year Golden Residency.
Foreign retirees can also qualify if they receive a pension of at least BHD 4,000, or approximately $10,600. Foreign employees and retirees already residing in Bahrain need a basic salary of at least BHD 2,000, or approximately $5,300.
5. UAE
Tax rules. The UAE has no personal income tax. Salaries, personal investment income, and real estate investment income earned by individuals in their personal capacity are free of tax.
Individuals who conduct business in the UAE may become subject to corporate tax if their annual business turnover exceeds AED 1 million. The standard corporate tax rate is 9% on taxable income above AED 375,000[11]Source: UAE Federal Tax Authority — Basis of Taxation: Natural Persons.
How tax residence is established in the UAE. A foreign national can become a tax resident if they:
- spend at least 183 days in the UAE within 12 consecutive months;
- are GCC national or hold a valid UAE residence permit, while also having a permanent home, job or business in the country, and spend at least 90 days in the UAE;
- have their usual place of residence and the centre of their personal and financial interests in the UAE[12]Source: UAE Federal Tax Authority — Cabinet Decision No. 85 of 2022 on Determination of Tax Residency.
Pathway to residence. The UAE does not offer citizenship by investment, but foreign investors can obtain renewable residence permits.
In Dubai, a sole owner of real estate can apply for a 2-year investor residence visa regardless of the property's value. For jointly owned property, the applicant's share must be worth at least AED 400,000.
Investors who own one or more properties in the UAE worth at least AED 2 million can qualify for a 10-year Golden Residency[13]Source: Dubai Land Department — Golden Visa Application for Investors.
The United Arab Emirates offers multiple entertainment and educational facilities, investment options for businesses worldwide, and government support for expats. However, as a primarily Islamic country, the Emirates has rules and traditions to respect: women are advised to dress modestly everywhere, but in the beach area, public displays of affection are generally frowned upon, and alcohol purchasing is regulated.
6. Bahamas
Tax rules. The Bahamas has no personal income tax or capital gains tax. The standard VAT rate is 10%. Businesses pay an annual business licence tax of 0.5 to 1.25% based on turnover[14]Source: Bahamas Department of Inland Revenue — Business Licence FAQs.
How tax residence is established in the Bahamas. The Bahamas does not impose formal tax-residency requirements on individuals.
In September 2026, the government announced plans to introduce a Tax Residency Certificate for permanent residents who spend at least 90 days per calendar year in the country. The proposed scheme has not yet entered into force.
Pathway to residence in the Bahamas. The Bahamas does not offer citizenship by investment. Foreign investors can apply for economic permanent residence by investing at least $1 million in Bahamian real estate, government bonds, or a combination of the two. The investment must remain in place for at least 10 years.
7. Bermuda
Tax rules. Bermuda has no personal income tax or VAT. Nevertheless, this does not mean that employment income is entirely tax-free.
Bermuda imposes payroll tax on employment and self-employment income. The employee portion is calculated at progressive rates of 0.25 to 12.5%, while employer rates range from 0 to 9.75%, depending on the type and size of the business. Employers are responsible for paying the full payroll tax but may deduct the employee portion from salaries.
Since 2025, Bermuda has also charged a 15% corporate income tax on companies belonging to multinational groups with annual consolidated revenue of at least €750 million in at least two of the previous four financial years. Businesses outside this regime generally do not pay corporate income tax[15]Source: Government of Bermuda — Payroll tax rates for 2026/27.
How tax residence is established in Bermuda. Bermuda has no formal tax-residency requirements for individuals because it does not levy personal income tax. There is no minimum number of days an individual must spend in the territory to qualify as a resident for personal income tax purposes.
Pathway to residence in Bermuda. Foreign investors can apply for an Economic Investment Residential Certificate by making a qualifying investment of at least $2.5 million in Bermuda. Successful applicants can obtain the right to reside in the territory indefinitely without waiting five years. Applicants must also donate at least $25,000 to a registered Bermuda charity, either as part of or in addition to their qualifying investment.
8. Cayman Islands
Tax rules. The Cayman Islands have no personal income tax, corporate income tax, capital gains tax, inheritance tax, or VAT.
How tax residence is established in the Cayman Islands. There is no formal test for determining an individual's tax residence or minimum stay requirement for tax purposes.
Pathway to residence in the Cayman Islands. Foreign investors can obtain permanent residence by investing at least CI$2 million in developed real estate. They must keep this investment while holding the Certificate of Permanent Residence for Persons of Independent Means.[16]Source: Cayman Islands Government — Immigration Regulations 2025 Revision
9. Monaco
Tax rules. Monaco has no personal income tax, wealth tax, land tax, or housing tax for most residents[17]Source: Prince’s Government of Monaco — taxation framework for individuals and businesses.
Companies carrying out industrial or commercial activities and earning more than 25% of their turnover outside Monaco pay corporate tax at 25%. The standard VAT rate is 20%.
How tax residence is established in Monaco. A person can obtain a certificate of residence for tax purposes if they:
- spend more than 183 days a year in Monaco;
- have their main centre of activity there, spend more time in Monaco than in any other country;
- have their home in Monaco.
Pathway to residence. Monaco does not offer residence or citizenship by investment.
Foreigners can apply for a residence permit by demonstrating sufficient financial resources and securing accommodation in Monaco, either through property ownership or a rental agreement. They can provide proof of employment income, a certificate from a Monaco bank confirming adequate savings, or evidence of financial support from a third party.
There is no statutory minimum income or bank deposit requirement. In practice, banks commonly require deposits of around €500,000 before issuing a certificate confirming sufficient savings, some private banks require €1 million or more.
10. Saudi Arabia
Tax rules. Saudi Arabia does not levy personal income tax on employment income. The standard corporate income-tax rate for foreign-owned businesses is 20%.
Companies producing oil and hydrocarbons pay tax at rates of 50 to 85%, depending on their capital. The standard VAT rate is 15%[18]Source: Ministry of Investment of Saudi Arabia — Tax Law and Regulations.
How tax residence is established in Saudi Arabia. An individual becomes a tax resident if one of the conditions apply:
- they have a permanent home in Saudi Arabia and spend at least 30 days there during the tax year;
- they do not have a permanent home in the country but spend at least 183 days there during the tax year.
Days do not have to be consecutive.
Pathway to residence in Saudi Arabia. Business investors can receive permanent Premium Residency by investing at least SAR 7 million in Saudi business activities and employing at least 10 people. They must maintain both the investment and the jobs for the first two years. Property owners can qualify by owning or using residential property worth at least SAR 4 million.
11. British Virgin Islands
Tax rules. The British Virgin Islands have a 0% personal income tax rate and do not levy corporate income tax, capital gains tax, or withholding tax.
The territory is included among jurisdictions with zero income tax because its personal income tax rate is 0%. Nevertheless, this does not mean that employment income is entirely tax-free.
Employment and self-employment income earned in the territory is subject to payroll tax at a total rate of 10 to 14%, depending on the employer category. Employers may deduct 8% of taxable remuneration from employees' salaries and pay the remaining share themselves. The first $10,000 of annual remuneration is exempt from payroll tax[19]Source: Government of the Virgin Islands — Guide to Payroll Tax.
How tax residence is established. The British Virgin Islands do not apply a formal residence test for personal income tax purposes. An individual's residence or domicile generally does not affect their tax liability in the territory, and there is no minimum stay requirement to qualify for the 0% personal income tax rate.
Pathway to residence and citizenship. The British Virgin Islands do not offer residence or citizenship by investment.
Foreigners can live in the territory under immigration statuses linked to employment, study, or family circumstances. Self-employed foreigners generally need a work permit and the required business licences.
12. Turks and Caicos Islands
Tax rules. The Turks and Caicos Islands do not levy personal income tax, corporate income tax, capital gains tax, or inheritance tax.
Businesses must obtain an annual business licence, with fees ranging from $10 to $7,500 depending on the activity. Some sectors also pay specific taxes of 2.5 to 12%[20]Source: Turks and Caicos Islands Revenue Department — Business Licence.
How tax residence is established. The territory has no statutory criteria for determining personal tax residence, as it does not impose direct income taxes.
Pathway to residence and citizenship. Foreign investors can obtain permanent residence by investment in real estate or business. The minimum property investment is:
- $300,000 on Grand Turk, Salt Cay, South Caicos, Middle Caicos, or North Caicos;
- $1 million on the other islands.
Business investment starts at $750,000 or $1.5 million depending on the island, and at least 60% of employees must not require work permits.
13. Brunei
Tax rules. Brunei does not levy personal income tax or capital gains tax. Companies pay corporate income tax at 18.5% of chargeable income[21]Source: Brunei Ministry of Finance and Economy — Corporate Tax FAQs.
How tax residence is established in Brunei. An individual is generally considered a tax resident if they spend at least 183 days there during the year preceding the year of assessment. Employment in Brunei for at least 183 days also meets the test.
Pathway to residence and citizenship. Brunei does not offer residence or citizenship by investment. Foreigners can live in the country under routes such as a work pass or a dependant pass.
14. Kuwait
Tax rules. Kuwait does not charge personal income tax. Foreign companies generally pay corporate income tax at 15% of net taxable income.
Since 2025, multinational groups with annual global revenue above €750 million are also subject to Kuwait’s 15% domestic minimum top-up tax rules.
How tax residence is established in Kuwait. An individual can obtain a Kuwaiti Tax Residency Certificate if they spend at least 183 days in the country during the relevant fiscal year. The days can be continuous or intermittent.
Pathway to residence in Kuwait. Kuwait does not offer citizenship by investment.
Since June 2026, foreign investors and certain senior executives in companies licensed by the Kuwait Direct Investment Promotion Authority can obtain residence permits for up to 15 years. To qualify, the licensed company must maintain at least KWD 5 million in investment, at least KWD 1 million in capital, active operations in Kuwait, and the required minimum employment level for Kuwaiti nationals[22]Source: Kuwait Direct Investment Promotion Authority — Kuwait Strengthens Long-Term Residency.
15. Qatar
Tax rules. Qatar does not tax salaries, wages, or allowances received by individuals.
Income from taxable business activity is generally taxed at 10%, while petroleum and petrochemical activities are taxed at a minimum rate of 35%.
Capital gains on real estate or securities held by individuals outside a taxable business are exempt.
How tax residence is established in Qatar. An individual qualifies as a tax resident if one of these conditions applies:
- they have a permanent home in Qatar;
- they spend more than 183 days there within any 12-month period;
- they have their centre of vital interests in the country.
Pathway to residence in Qatar. There is no citizenship by investment route operating in Qatar.
Foreigners can obtain residence by buying property in designated freehold areas. Property worth more than QAR 730,000 qualifies for a residence permit. Real estate worth more than QAR 3.65 million grants residence with additional benefits similar to permanent residence. Property owners must spend at least 90 days a year in Qatar to keep these benefits.
16. Anguilla
Tax rules. Anguilla does not levy personal income tax, corporate income tax, or capital gains tax. The standard General Services Tax rate is 13%.
General Services Tax is an indirect tax on services rather than personal income. It applies to a range of services, including hotel accommodation, tourism activities, legal and accounting services, construction, and telecommunications. Registered businesses add this tax to the prices charged to customers and remit the collected tax to the government.
How tax residence is established in Anguilla. Since Anguilla does not levy personal income tax, it has no general personal income-tax residence test.
Ordinary immigration residence does not automatically entitle an individual to a tax-residence certificate.
For formal certification, Anguilla offers a separate High Value Resident programme. Applicants must:
- pay an annual lump-sum tax of $75,000 for five years;
- own property in Anguilla worth at least $400,000;
- spend at least 45 days a year in Anguilla;
- spend fewer than 183 days a year in any other single country;
- maintain their centre of vital interests and genuine links in Anguilla.
The tax residence certificate is issued annually[23]Source: Select Anguilla — Tax Residency.
Pathway to residence and citizenship. Anguilla offers permanent residence by investment. A single applicant can contribute at least $150,000 to the Capital Development Fund or buy real estate worth at least $750,000 for a family of four.
17. Oman
Tax rules. Oman does not currently levy personal income tax. A 5% personal income tax will take effect in 2028 on taxable annual income above OMR 42,000[24]Source: Oman Tax Authority — Issuance of Personal Income Tax Law.
Companies generally pay corporate income tax at 15%, while qualifying small businesses can pay 3%. The standard VAT rate is 5%.
How tax residence is established in Oman. An individual becomes a tax resident if they spend at least 183 days in Oman during the tax year. The days can be continuous or intermittent.
Pathway to residence and citizenship. Oman does not offer citizenship by investment. Foreign investors can obtain a renewable 10-year Golden Residency by investing at least about $520,000 through routes such as real estate, an Omani company, government bonds, listed securities, or a fixed-term bank deposit.
The programme also includes routes for investors who employ at least 50 Omani nationals or receive a nomination from an invested company.
Don’t know where to start?
Download our one-page pathways navigator to compare the options and pick the best one
Low-tax alternatives to countries with zero income tax
Countries with no personal income tax are not the only option for individuals seeking to reduce their tax burden. Some jurisdictions offer relatively low income tax rates, generous tax-free allowances, or preferential tax regimes for foreign residents.
Malta, Cyprus, Montenegro, Andorra, and Singapore are examples of such alternatives. Although they levy personal income tax, individuals may benefit from exemptions or reduced rates depending on their income, tax residency, and eligibility for special tax regimes.
Malta
An individual's tax rates are progressive, ranging between 0% and 35%.
The standard corporate income tax rate in Malta is 35%. Shareholders can typically reclaim 6/7 of the tax paid on distributed trading profits, reducing the effective rate to 5%.
A full 100% refund may apply to profits from qualifying shareholdings, typically where a Maltese company owns at least 5% of another company's equity shares and holds specified shareholder rights.
Alternatively, companies can opt for a 15% final corporate tax regime introduced in 2025, under which shareholders cannot claim tax refunds.
The Malta Global Residence Programme allows one to get the country’s residence permit. The residency entitles you to pay taxes on Malta, which are different from the standard tax rates. Participants of the programme enjoy a special tax regime:
- 15% on the income earned abroad and transferred to Malta, at least €15,000 per annum;
- 0% on global income not transferred to Malta;
- 35% of the income earned in Malta.

Trusted by 10,000+ investors
Check your eligibility for the Malta Global Residence Programme
Cyprus
Depending on income, Cyprus’s tax rate varies from 0 to 35%. The first €22,000 of taxable income is exempt, and income above €72,000 is taxed at the top rate of 35%[25]Source: Cyprus Tax Department — Individual Income Tax Return and 2026 tax bands.
Cyprus tax residents are generally taxed on income earned both in Cyprus and abroad, although exemptions apply to certain types of income. For example, profits from the sale of securities are exempt from income tax. The corporate tax rate is one of the lowest in Europe — 15%.
One can become a Cyprus tax resident if they spend 60+ days a year without spending more than 183 days a year in any other country.
Montenegro
Personal income tax in Montenegro varies by type and amount of income. Employment income is taxed at 0 to 15%, while income from property, capital, and capital gains is generally taxed at 15%[26]Source: Government of Montenegro — Personal Income Tax Act.
Corporate income tax is progressive, with rates of 9 to 15%. The general annual property-tax rate ranges from 0.25 to 1% of the property's market value, although higher rates apply to some categories of property.
Andorra
Andorra is among the lowest-tax countries in Europe. Andorra's basic personal income tax rate is 10% for resident individuals. Effectively, it applies to income above €40,000. Lower income residents pay less:
- income up to €24,000 is exempt;
- income between €24,001 and 40,000 is taxed at 5%[27]Source: Government of Andorra — Personal income-tax rates.
The Andorran corporate tax rate is also 10%.
Instead of sales tax, a value-added tax is applied to goods and services. In Andorra, the VAT is the lowest anywhere in Europe, with a general rate of 4.5%.
Singapore
Singapore tax residents pay personal income tax at progressive rates from 0 to 24%. The standard corporate income-tax rate is 17%[28]Source: Inland Revenue Authority of Singapore — Individual Income Tax Rates.
Companies can reduce their taxable income through the Partial Tax Exemption scheme: 75% of the first SGD 10,000 of normal chargeable income and 50% of the next SGD 190,000 are exempt. Qualifying start-ups receive a separate exemption during their first three assessment years.
Is it possible to optimise taxes without moving abroad?
Individuals can legally reduce their tax burden without relocating to another country. One option is to use tax deductions, allowances, and exemptions available under local laws. For example, self-employed individuals may deduct qualifying business expenses, while pension contributions can reduce taxable income in some countries.
Double taxation treaties provide another opportunity for tax optimisation. They may reduce withholding taxes on foreign dividends, interest, and royalties or allow individuals to claim tax credits for taxes paid abroad. Business owners may also benefit from corporate tax incentives or establishing companies in lower-tax jurisdictions, provided these companies conduct genuine business activities there.
Nevertheless, obtaining a foreign residence permit or registering a company abroad does not automatically reduce tax obligations. Individuals who continue living and working in their home country may remain tax residents there and be required to pay tax on their worldwide income.
Vladlena Baranova,
Head of Legal & AML Compliance Department, CAMS, IMCM
Even after establishing tax residence abroad, individuals may still owe taxes in countries where their income originates. For example, rental income is generally taxable where the property is located, while foreign dividends may be subject to withholding tax.
Similarly, a company registered abroad may still be taxed in another country if its management and business operations are based there. Before choosing a tax optimisation strategy, individuals should assess their tax-residency status, sources of income, available exemptions, and applicable double taxation treaties.
Summary of zero-income tax countries
- There are 17 tax-free countries, which means they have zero income tax. At least four of these countries offer investment-based citizenship or residence paths to foreigners — Antigua and Barbuda, St Kitts and Nevis, the UAE, and Vanuatu.
- Among the countries with the lowest tax rates in the world are Malta, Cyprus, Andorra, Montenegro, and Singapore.
- Aside from zero income tax, in Antigua and Barbuda, individuals are also free from paying taxes on wealth, capital gains, and inheritance.
- To optimise taxes without relocation, individuals should look into possible deductions and returns in their country and can also consider moving their business to a country with lower taxes.
- Before choosing the country for tax optimisation, check if your primary country of residence has a double tax treaty with the country you want to move to or open a business in.
Immigrant Invest is a licensed agent for citizenship and residence by investment programs in the EU, the Caribbean, Asia, and the Middle East. Take advantage of our global 15-year expertise — schedule a meeting with our investment programs experts.

 Trusted by 10,000+ investors